



ANGEL ASSET MANAGEMENT
What Is Medicare Advantage? A Guide to Part C
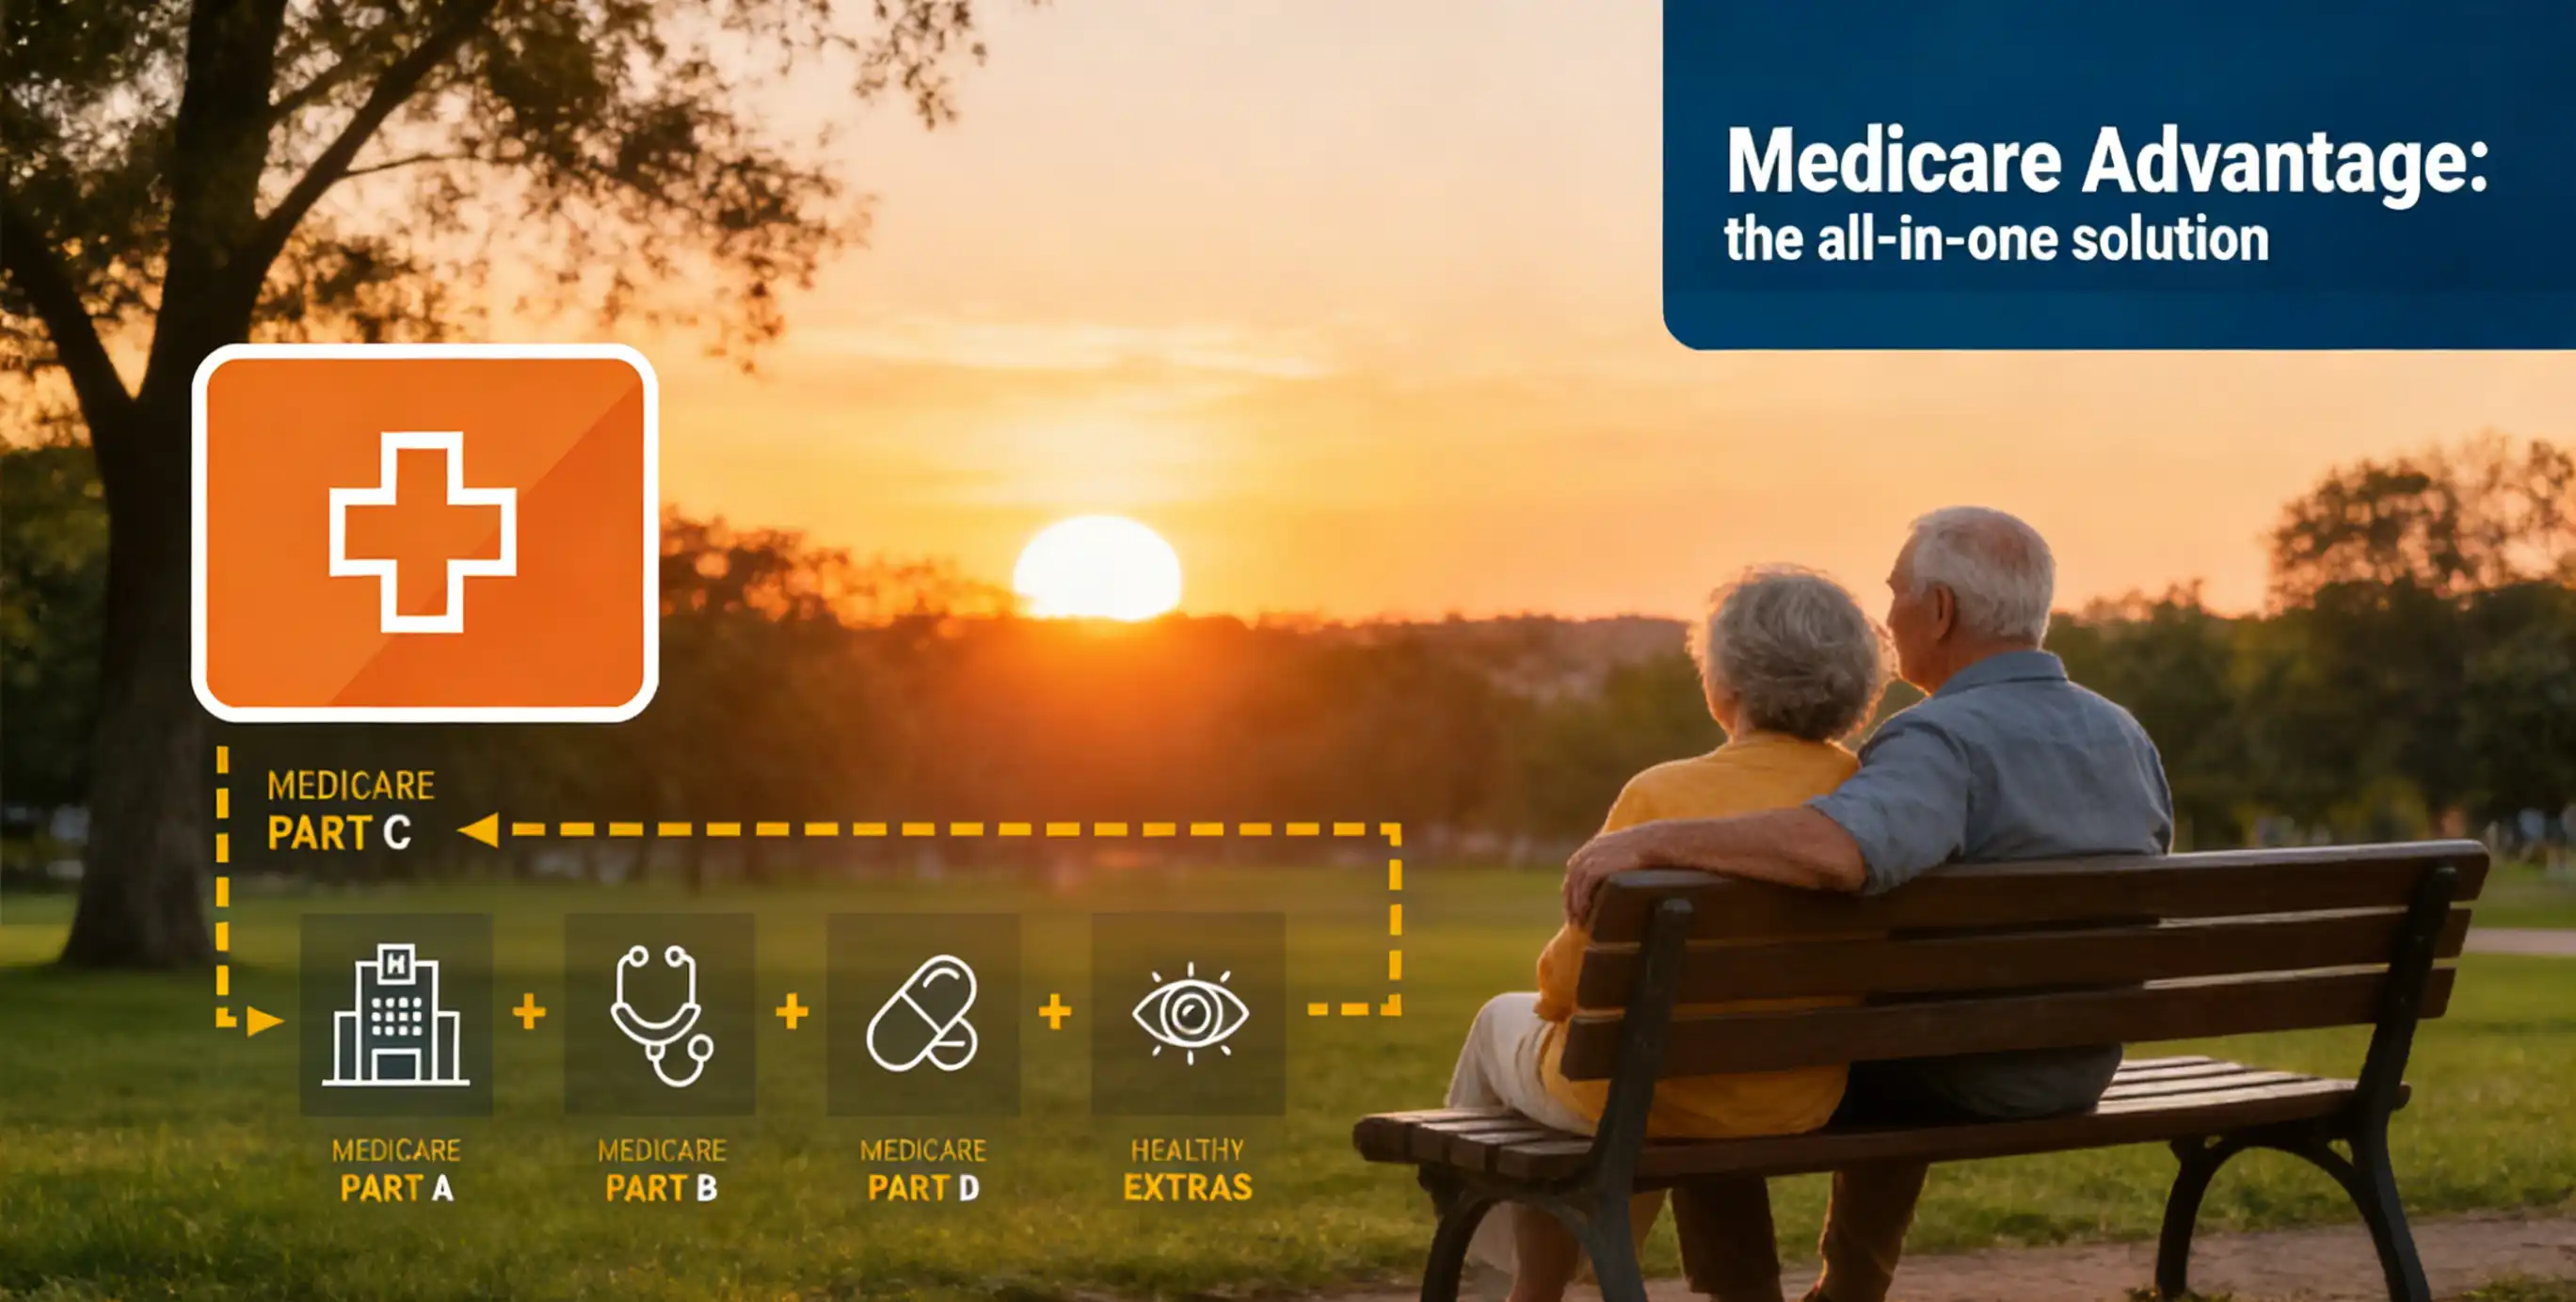
Medicare Advantage, or Part C, provides Part A and Part B benefits through a Medicare-approved private insurer. A plan may combine hospital, medical, drug and extra benefits, but that does not make every service free.
1. How Does It Work?
Joining generally requires both Part A and Part B and residence in the plan's service area. You still have Medicare and generally pay the Part B premium. Plans must provide required Part A and B benefits; most include Part D. Dental, vision, hearing, transportation, fitness and over-the-counter benefits vary.
2. Using Care
You generally present the plan card. Provider and pharmacy networks, referrals or prior authorization may apply. Emergency and urgent care have special protections, but routine out-of-network services may be uncovered or more expensive.
3. A $0 Premium Does Not Mean $0 Costs
You generally still pay the Part B premium and may owe deductibles, office or hospital copays, coinsurance and drug costs. Uncovered services are your responsibility. The plan's annual medical out-of-pocket limit applies to covered Part A and B services; Part D drug costs follow separate rules and do not count toward that medical limit.
4. Common Plan Types
HMOs generally use in-network doctors and may require specialist referrals. PPOs generally permit out-of-network care at higher cost. Special Needs Plans serve eligible people with certain chronic conditions, institutional needs or both Medicare and Medicaid. Availability varies by ZIP code.
5. Who Might Consider It?
It may suit someone who wants medical and drug benefits together, values a medical out-of-pocket limit, accepts a local network or wants specific extra benefits. Check providers, prescriptions and travel needs.
6. Important Limitations
Providers can leave a network. Some tests, operations or rehabilitation need prior authorization. Out-of-network PPO services can cost more; routine out-of-state care may be restricted. Extra benefits may have dollar, visit, provider or geographic limits.
7. Comparison Checklist
Check your primary and specialist doctors, hospitals and prescriptions; tiers; office, hospital, imaging, ambulance and rehabilitation costs; referrals and authorization; in- and out-of-network limits; and how dental, vision and hearing benefits work.
8. When Can You Join or Change?
You may choose a plan during initial eligibility. Medicare Open Enrollment, October 15–December 7, generally permits a change effective January 1. People already enrolled in Medicare Advantage may generally make one change or return to Original Medicare and join Part D during the January 1–March 31 Medicare Advantage Open Enrollment Period. Moves, Medicaid changes and other events may create special enrollment periods.
9. Returning to Original Medicare
Leaving Medicare Advantage does not guarantee the ability to buy Medigap. Outside the federal six-month Medigap open enrollment period, insurers may use health underwriting unless a federal guaranteed-issue or trial right or state protection applies. Check timing, Part D, Medigap rights and effective dates before ending current coverage.
10. Choosing a Plan
Look beyond extra benefits: confirm that the plan covers the doctors, hospitals and prescriptions you use and that expected total costs fit your budget.
This is general education, not legal, tax, medical or individual insurance advice. Networks, benefits, formularies, costs and eligibility change; consult Medicare and the plan's Evidence of Coverage.
PUT YOUR KNOWLEDGE INTO PRACTICE
Your next step
Discuss your next step. The consultation form will identify this article; you can edit or remove that context.
Request Medicare guidance →